Short answer: Most Tucson homeowners finance a pool with one of three things: a pool loan, a home equity loan or HELOC, or a cash-out refinance. A pool loan is usually the fastest and doesn’t put your house up as collateral. Home equity options can carry a lower rate but take longer to approve. The smart order is: get a design and an itemized quote first, then compare loans on that exact number, then sign the build contract once your financing is lined up.
Below is how each option works, what the monthly payment can look like, and when to apply so financing never holds up your build.
What are the main ways to finance a pool in Arizona?
| Option | How it works | Good to know |
|---|---|---|
| Pool loan | A loan made for pool and backyard projects, usually not tied to your home’s equity. | Often the fastest to set up. The rate and term depend on your credit. |
| Home equity loan | A lump-sum loan secured by your home, usually at a fixed rate. | Rates can be lower because your home is the collateral. Approval and closing take longer. |
| HELOC (home equity line of credit) | A credit line secured by your home. You draw what you need. | Handy when payments are spread over a build, but the rate is often variable. |
| Cash-out refinance | Replace your mortgage with a larger one and use the difference. | Makes the most sense when it doesn’t raise the rate on your whole mortgage. |
| Cash or a mix | Pay part in cash and finance the rest. | A smaller loan means a smaller payment and less interest. |
Plenty of people mix these. For example, they pay for the pool with a loan and add the outdoor kitchen later with cash.
Pool loan or HELOC: which one should you pick?
Lay the offers side by side on the same project amount and compare:
- Rate type. Pool loans and home equity loans are often fixed. HELOCs are often variable, so the payment can change.
- Collateral. A pool loan usually isn’t secured by your home. A home equity loan, HELOC or refinance is.
- Speed. Pool loans can often be approved quickly. Home equity options usually need an appraisal and a closing.
- Fees. Ask about origination fees, closing costs and any prepayment penalty.
- Total cost. The lowest payment isn’t always the cheapest loan. Look at the total interest over the term too.
If you’re unsure, ask two lenders for quotes on the same amount and term. The difference usually becomes obvious quickly. Every lender looks at your situation differently, so treat the lender’s numbers as the real ones.
What would the monthly payment be on a pool?
Most new custom concrete pools we build in Southern Arizona run about $40,000 to $120,000+, depending on size, finish, decking and features (see our pool cost guide). Here is what those amounts look like at 6.99% APR, the example rate our calculator starts with:
| Amount financed | 10 years | 15 years | 20 years |
|---|---|---|---|
| $40,000 | about $464 / mo | about $359 / mo | about $310 / mo |
| $80,000 | about $928 / mo | about $719 / mo | about $620 / mo |
| $120,000 | about $1,393 / mo | about $1,078 / mo | about $930 / mo |
The term changes the total cost a lot. On $60,000 at 6.99%, a 15-year loan comes to about $539 a month and about $37,000 in total interest. A shorter term raises the payment but cuts that interest.
These are examples only. Your real rate, term and payment come from the lender and depend on your credit, the loan type and the amount. Try your own numbers in our pool loan calculator. You can change the amount, rate and term there.
When should you apply for pool financing?
Here is the order that keeps things moving:
- Get a design and an itemized quote. Lenders want a real number, and you want to borrow for the pool you’ll actually build. Our free 3D design visit gives you both.
- Talk to a lender or two. Many lenders can tell you early what you are likely to qualify for. Ask how the money is released: all at once, or in stages as the build moves along.
- Sign the build contract once the financing is lined up. That way you aren’t committed to a schedule your loan can’t keep up with.
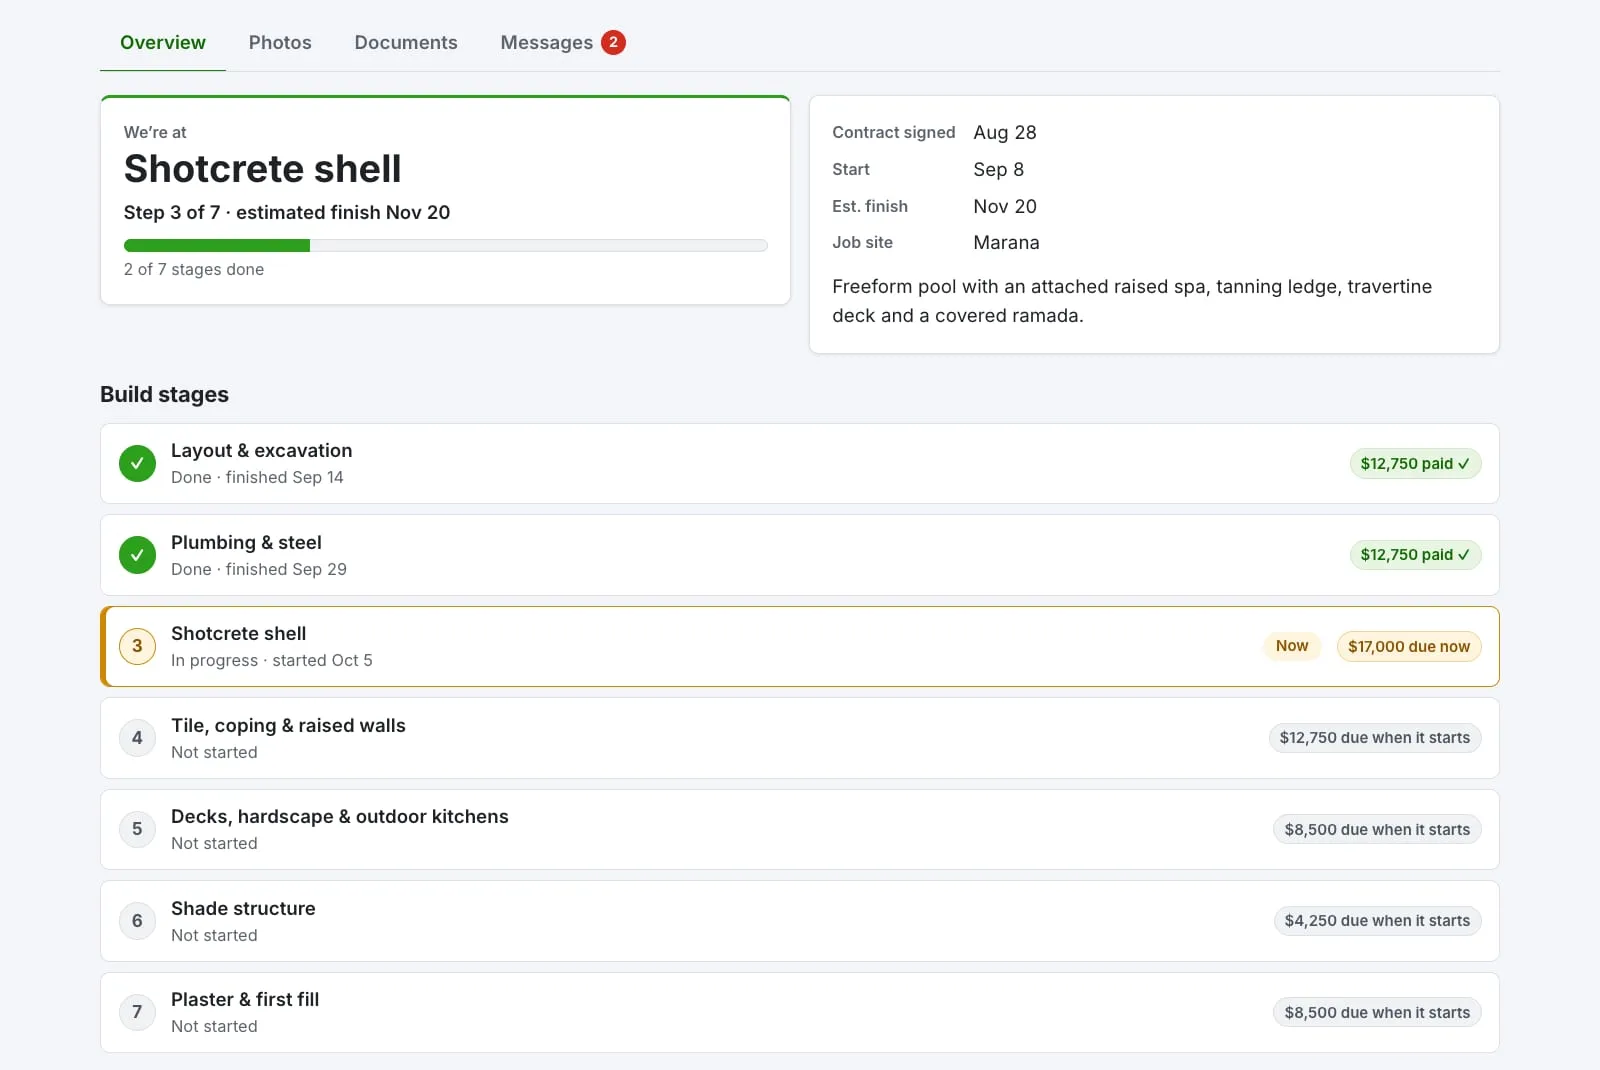
- Permits and the build. Permits come next (see our Tucson pool permit guide), then construction. In Arizona, payments on a pool contract are tied to finished stages of the build. Our guide on comparing pool bids explains the deposit rules.
Fall and winter are a good time to start. You can line up financing and permits now, and be swimming by the hot months.
What do lenders look at?
Every lender is different, but most look at the same basics:
- Your credit history and score. This usually drives the rate you’re offered.
- Income and existing debts. Lenders want the new payment to fit your budget.
- Home equity. This matters for home equity loans, HELOCs and refinances.
- The project itself. A clear, itemized quote from a licensed contractor helps. Our ROC licenses are listed on every page of this site.
If your credit needs work, it can pay to fix errors on your report or pay down a card balance before you apply.
Should you finance just the pool, or the whole backyard?
Think about the whole yard before you settle on a loan amount. A pool is rarely just the pool:
- Decking around the pool. See our decking materials guide.
- A pool barrier. Arizona law and local codes require one in most cases, and we build every barrier to at least 5 feet. See our pool barrier rules guide.
- Extras you may want now or later: a spa, a heater, water or fire features, an outdoor kitchen, turf and plants.
Building it all at once usually costs less than bringing a crew and equipment back a second time. Phasing can still be smart, though. Ask us to run the gas line, power or plumbing now for a heater or spa you’ll add later. Then the second phase is quick and doesn’t mean tearing up a new deck.
How can you keep the loan amount down?
- Size the pool for how you’ll use it. A smaller pool with a great tanning ledge often gets more use than a big pool nobody swims laps in. See our small pool and plunge pool guide.
- Pick where to spend. A standard interior finish and a modest deck can free up budget for the feature you really want.
- Settle the design before you sign. Changing things mid-build costs more than getting them right on paper.
- Compare bids by what they include. A low number that leaves out decking or the barrier costs more later. Our bid comparison checklist helps.
Also budget for owning the pool: water, power, chemicals and upkeep. See what it costs to run a pool in Tucson.
How Meraki Pools AZ helps with financing
- An itemized quote that you and your lender can read line by line.
- Lending partners if you want them. Apply directly with Lyon Financial or Credit Union West from our financing page, or bring your own bank or credit union. We can work with any lender.
- A free on-site design visit, with 3D and VR design, so you finance the backyard you actually want.
Ready to get a real number to take to a lender? Request your free design consult or call (520) 342-8335.
Put this guide to work
Planning your own project? See our Custom Pool Construction in Tucson, Pool Decks: Travertine & Pavers in Tucson and Block Walls & Pool Barrier Walls in Tucson.
Frequently asked questions
What is the best way to finance a pool in Arizona?
There isn't one best way. A pool loan is usually the fastest to set up and doesn't use your home as collateral. A home equity loan or HELOC can have a lower rate because it is secured by your home, but approval takes longer. A cash-out refinance can make sense when it doesn't raise the rate on your whole mortgage. Compare the rate, fees, term and monthly payment on the same project amount.
How long can you finance a pool?
Terms depend on the lender and the loan type. Pool loans are often set up over several years to a couple of decades, and home equity loans and refinances can run longer. A shorter term means a higher payment and less total interest. A longer term lowers the payment but costs more over time.
Do I need a down payment to finance a pool?
It depends on the lender and the loan type. Some pool loans can cover the whole project, while home equity options depend on how much equity you have. Ask the lender how much of the project the loan can cover before you sign a build contract.
Can I finance the deck, walls and landscaping too?
Often, yes. Ask the lender what the loan can cover. An itemized quote that lists the pool, spa, decking, barrier wall, outdoor kitchen and landscaping makes it easy for the lender to see exactly what is being built.
Is pool loan interest tax deductible?
Interest on an unsecured personal loan generally isn't deductible. Interest on a loan secured by your home may be deductible in some cases when the money is used to improve that home. Rules change, so ask your tax preparer before you choose a loan for that reason.
Do I have to use Meraki's lending partners?
No. You can apply with our partners, Lyon Financial or Credit Union West, or use your own bank or credit union. You apply with the lender directly either way, and we can work with any lender you choose.